
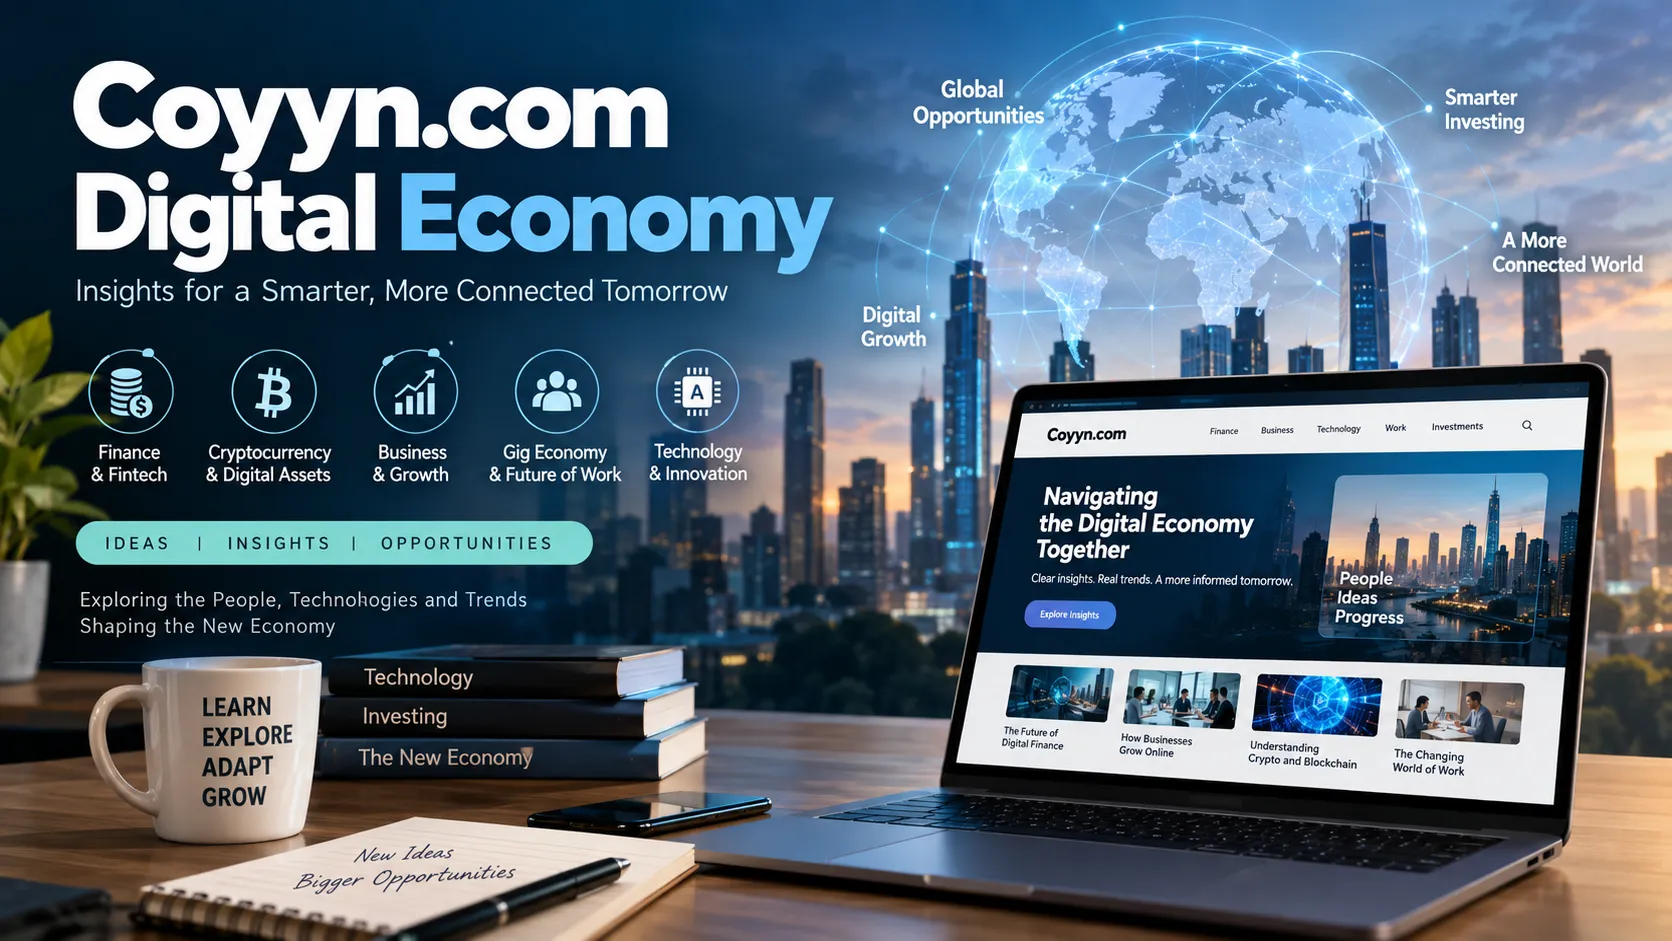
The coyyn.com digital economy refers primarily to Coyyn’s editorial coverage of digital finance, cryptocurrency, online business, investing, fintech, and the changing world of work. Coyyn is not a bank, crypto exchange, brokerage, or investment platform. Its own current material describes the website as an informational and editorial resource designed to explain how technology is reshaping money, business, capital, and employment.
That distinction matters. Some descriptions across the site use phrases such as “Coyyn Banking” or “Coyyn Capital,” which could sound like financial products when read in isolation. However, Coyyn’s detailed September 2026 guide explicitly states that the site does not directly provide banking, brokerage, cryptocurrency exchange, or investment-advisory services.
What Is the Coyyn.com Digital Economy?
The phrase coyyn.com digital economy is best understood as a content framework rather than a separate economy or financial network.
Coyyn organizes its coverage around several connected areas, including digital finance and banking, cryptocurrency, business growth, investments, digital assets, and the gig economy. The website says its aim is to help readers understand how these areas increasingly overlap in a technology-driven economy.
For example, a freelancer may use digital payment systems, operate an online business, manage irregular income and interact with financial technology platforms at the same time. Likewise, a small business owner might rely on e-commerce, cloud software, online payments, remote workers and digital marketing as part of one connected operating model.
The broader digital economy works in a similar way. It includes economic activities enabled or substantially influenced by digital technologies, networks, data and online platforms.
What Coyyn.com Actually Is
Coyyn currently identifies itself as an editorial platform focused on digital capital, digital finance and the technology-driven new economy. Its September 2026 overview separates its coverage into five broad pillars:
| Coyyn content area | Main subjects |
|---|---|
| Cryptocurrency | Blockchain, crypto assets, wallets, exchanges, stablecoins and regulation |
| Digital Finance & Banking | Digital money, fintech, payments and online banking concepts |
| Business & Growth | Business formation, funding, digital tools, operations and growth |
| Assets & Investments | Traditional and alternative investments, digital assets and private markets |
| New Economy & Gig Economy | Freelancing, independent work, sharing economy and data economy |
Coyyn says these subjects are connected because modern financial and business decisions increasingly cross traditional boundaries.
The site also explicitly says it should be treated as a starting point for research rather than the final authority for financial decisions. Its disclaimer describes Coyyn as an informational website rather than a source of personalized financial advice.
How the Coyyn.com Digital Economy Relates to the Real Digital Economy
Coyyn’s coverage reflects several important parts of the wider digital economy, although the two should not be confused.
The global digital economy is much larger than cryptocurrency or digital banking. It includes e-commerce, digital services, software, telecommunications, online marketplaces, fintech, cloud computing, digital advertising, platform-based labor, artificial intelligence, digital public infrastructure and data-driven businesses.
The World Bank describes digital technologies as major forces transforming business, jobs, communications, finance, education and public services. Its research also emphasizes that the economic benefits of digitalization remain uneven because infrastructure, affordability and digital skills still vary greatly between countries and populations.
Coyyn therefore covers only selected parts of a much broader transformation.
Digital Finance and Payments
One of Coyyn’s strongest thematic links to the digital economy is financial technology.
Digital finance includes services such as mobile banking, digital wallets, online payments, peer-to-peer transfers, fintech applications and increasingly sophisticated digital payment infrastructure. Coyyn’s current digital-finance section discusses how these technologies affect the way individuals and businesses store, transfer and manage money.
This shift has practical implications. Businesses can sell to customers without requiring a physical store, freelancers can receive payments from clients in other markets, and consumers can move money through applications that operate around the clock.
These conveniences do not remove traditional financial risks. Fees, fraud, consumer protection, cybersecurity and regulatory differences still matter.
Cryptocurrency and Digital Assets
Cryptocurrency represents another prominent part of Coyyn’s digital-economy coverage.
Coyyn publishes educational material covering blockchain technology, cryptocurrency purchases, wallets, private-key security, stablecoins, decentralized exchanges and regulatory developments. Its own material recommends understanding both risks and basic investment principles instead of treating digital assets purely as speculative opportunities.
Digital assets are only one part of the digital economy, however.
A common misconception is that “digital economy” and “crypto economy” mean the same thing. They do not. Most digital economic activity still takes place through conventional currencies, businesses, banks, payment networks and technology companies.
Cryptocurrency adds another layer involving digitally represented assets and blockchain-based systems.
E-Commerce and Online Business
E-commerce is one of the most established components of the digital economy.
The OECD describes e-commerce as a cornerstone of the modern digital economy because it changes how consumers, businesses and governments conduct transactions. Its updated 2025 framework also recognizes the growing importance of digital intermediaries, subscriptions and AI-assisted ordering systems.
For businesses, digitalization can reduce some traditional barriers to entering a market. A small company can sell products online, run advertising campaigns, manage customers through cloud software and hire remote specialists without building the infrastructure previously required for similar operations.
Coyyn’s business coverage reflects this shift by discussing digital tools, automation, funding, customer management, business planning and modern operating models.
Gig Work and the Platform Economy
The changing labor market is another major theme behind the coyyn.com digital economy concept.
Coyyn covers freelancing, independent contracting, variable income, online work platforms and the wider gig economy. Its material recognizes that workers outside traditional salaried employment may need to handle budgeting, taxation, retirement planning and other financial responsibilities more independently.
Digital platforms have made it possible for workers and clients to connect across geographical boundaries. Designers, writers, programmers, consultants, virtual assistants and other professionals can increasingly provide services remotely.
There are also trade-offs. Platform workers can face income volatility, platform dependency, fees, limited employment benefits and changing rules regarding worker classification.
The Data Economy
Data is another fundamental resource in the digital economy.
Modern companies use data to personalize services, measure consumer behavior, train machine-learning systems, detect fraud, optimize logistics and make business decisions. Coyyn lists the “data economy” among the subjects covered under its wider new-economy category.
The economic value of data also creates questions about privacy, cybersecurity, ownership, consent and competition.
For consumers, this means many apparently free digital services still involve an economic exchange. Users may not pay money directly, but their activity can generate data that supports advertising, recommendation systems, product development or other commercial models.
Artificial Intelligence Is Becoming Part of the Digital Economy
Artificial intelligence is rapidly becoming part of the infrastructure behind digital businesses.
AI can automate customer support, analyze financial activity, generate content, improve fraud detection, assist programmers and help companies process large volumes of information. The World Bank’s recent digital research identifies AI as one of the most significant forces shaping the next stage of digital development.
Access remains uneven, however.
The benefits of AI depend partly on connectivity, computing resources, relevant data and human skills. Countries and companies without those foundations may participate in the digital economy without capturing the same amount of value as better-resourced competitors.
The Digital Economy Is Growing, but So Are Its Costs
The growth of digital commerce demonstrates the scale of the transformation.
UN Trade and Development reported that business e-commerce sales across 43 countries representing roughly three quarters of global GDP reached about $27 trillion in 2022, nearly 60% higher than in 2016.
But digital activity is not environmentally weightless.
Data centers, telecommunications infrastructure and billions of connected devices require electricity, water and raw materials. UNCTAD estimates that digital devices, data centers and ICT networks together account for roughly 6% to 12% of global electricity consumption.
That makes sustainability an increasingly important part of any serious discussion about the future digital economy.
Why the Digital Divide Still Matters
A digital economy can create opportunities only when people can actually access it.
The World Bank continues to highlight gaps in connectivity, affordability, digital literacy and infrastructure between countries and communities. Its research shows that digital adoption has grown rapidly, but the benefits are concentrated unevenly.
Small businesses can experience the same divide.
A company with reliable broadband, cloud software, digital-payment infrastructure and employees with strong technical skills has a major advantage over a business without those resources.
This is why digital transformation should not simply be measured by how many new apps or platforms exist. Meaningful participation also requires infrastructure, skills, affordable access, cybersecurity and effective regulatory systems.
Is Coyyn.com a Bank or Financial Platform?
No. Based on Coyyn’s own current editorial documentation, Coyyn.com is an informational and editorial website, not a bank, brokerage, cryptocurrency exchange or investment-advisory service.
This point is especially important because sections of the website use names such as “Coyyn Banking,” “Coyyn Capital” and “Coyyn Money.”
Readers should not assume from those names alone that Coyyn provides deposit accounts, regulated investment services, lending facilities or cryptocurrency custody. The more detailed Coyyn guide published on September 1, 2026 specifically defines the website as an educational resource rather than a provider of those financial services.
Can Coyyn.com Be Used for Financial Decisions?
Coyyn can be used to learn terminology or identify subjects that require further research, but financial decisions should not depend on a single editorial website.
Coyyn itself states that its material is informational and recommends professional guidance for personalized investment decisions. It also acknowledges that financial information can change and that content cannot guarantee complete accuracy indefinitely.
For regulated financial questions, the stronger approach is to verify important information through the relevant government regulator, financial institution, exchange, company filing or other primary source.
That is particularly important for:
- investment products and expected returns
- cryptocurrency platforms
- banking protections
- taxation
- interest rates and fees
- securities regulation
- business financing
- legal obligations
What Readers Should Check Before Trusting Digital-Economy Content
The digital economy changes quickly, so publication date and sourcing matter.
A useful article should clearly distinguish facts from predictions and explain where its information comes from. Claims involving investments, regulation, cybersecurity or financial products deserve extra scrutiny because inaccurate information can create real financial consequences.
For Coyyn or any comparable publication, check whether:
- Important claims link to primary or authoritative sources.
- Financial products are clearly distinguished from educational content.
- Publication and update dates are visible.
- Risks are explained alongside opportunities.
- Regulatory claims match current government guidance.
- Investment claims avoid guaranteed returns or unsupported predictions.
Coyyn’s own current guidance makes a similar point by advising readers to use the platform as a starting resource and confirm time-sensitive details such as regulations, market conditions and fees elsewhere.
What the Coyyn.com Digital Economy Means in Practice
In practical terms, coyyn.com digital economy is a way of grouping educational content about the financial and business systems emerging around digital technology.
Its subjects are connected by several broader changes:
Digital payments are reducing reliance on physical cash. E-commerce allows businesses to reach customers beyond local markets. Freelancing platforms allow skilled workers to find clients remotely. Blockchain has created new categories of digital assets. Cloud software lets companies operate with distributed teams. AI is automating more knowledge work. Data has become an economically important resource.
Coyyn attempts to explain these trends through a financial and business lens rather than operating the underlying economic infrastructure itself.
That is the clearest way to interpret the keyword without confusing an editorial publication with a regulated financial service.
Frequently Asked Questions
What is coyyn.com digital economy?
The coyyn.com digital economy refers to Coyyn’s educational coverage of digital finance, cryptocurrency, business, investments, fintech and the gig economy. It is not a separate currency, blockchain network or economic system.
Is Coyyn.com a real bank?
Coyyn says it is not a bank. Its current editorial guide describes Coyyn as an informational resource rather than a banking, brokerage, cryptocurrency-exchange or investment-advisory service.
Does Coyyn.com offer cryptocurrency trading?
Coyyn publishes information about cryptocurrencies and digital assets, but its own current documentation states that it is not a cryptocurrency exchange. Readers seeking to buy or trade digital assets would therefore need to use a separate service and independently evaluate its regulation and security.
What subjects does Coyyn cover?
Coyyn currently covers cryptocurrency, digital finance and banking, business growth, assets and investments, and the new economy, including freelancing, the sharing economy and the data economy.
Is Coyyn.com financial advice?
No. Coyyn’s disclaimer explicitly describes its content as informational rather than financial advice and recommends seeking qualified professional guidance for individualized financial decisions.
Why is the digital economy important?
The digital economy affects how people shop, work, communicate, receive payments, operate businesses and access financial services. Research from the World Bank, OECD and UNCTAD shows that digitalization is increasingly important to economic growth, commerce and innovation, while also creating challenges involving inequality, cybersecurity, regulation and environmental impact.
Also Read: SearchingForSingles org Review | What You Should Know in 2026

1 Comment
Pingback: Sinknews Com | What the Website Is and What to Know