
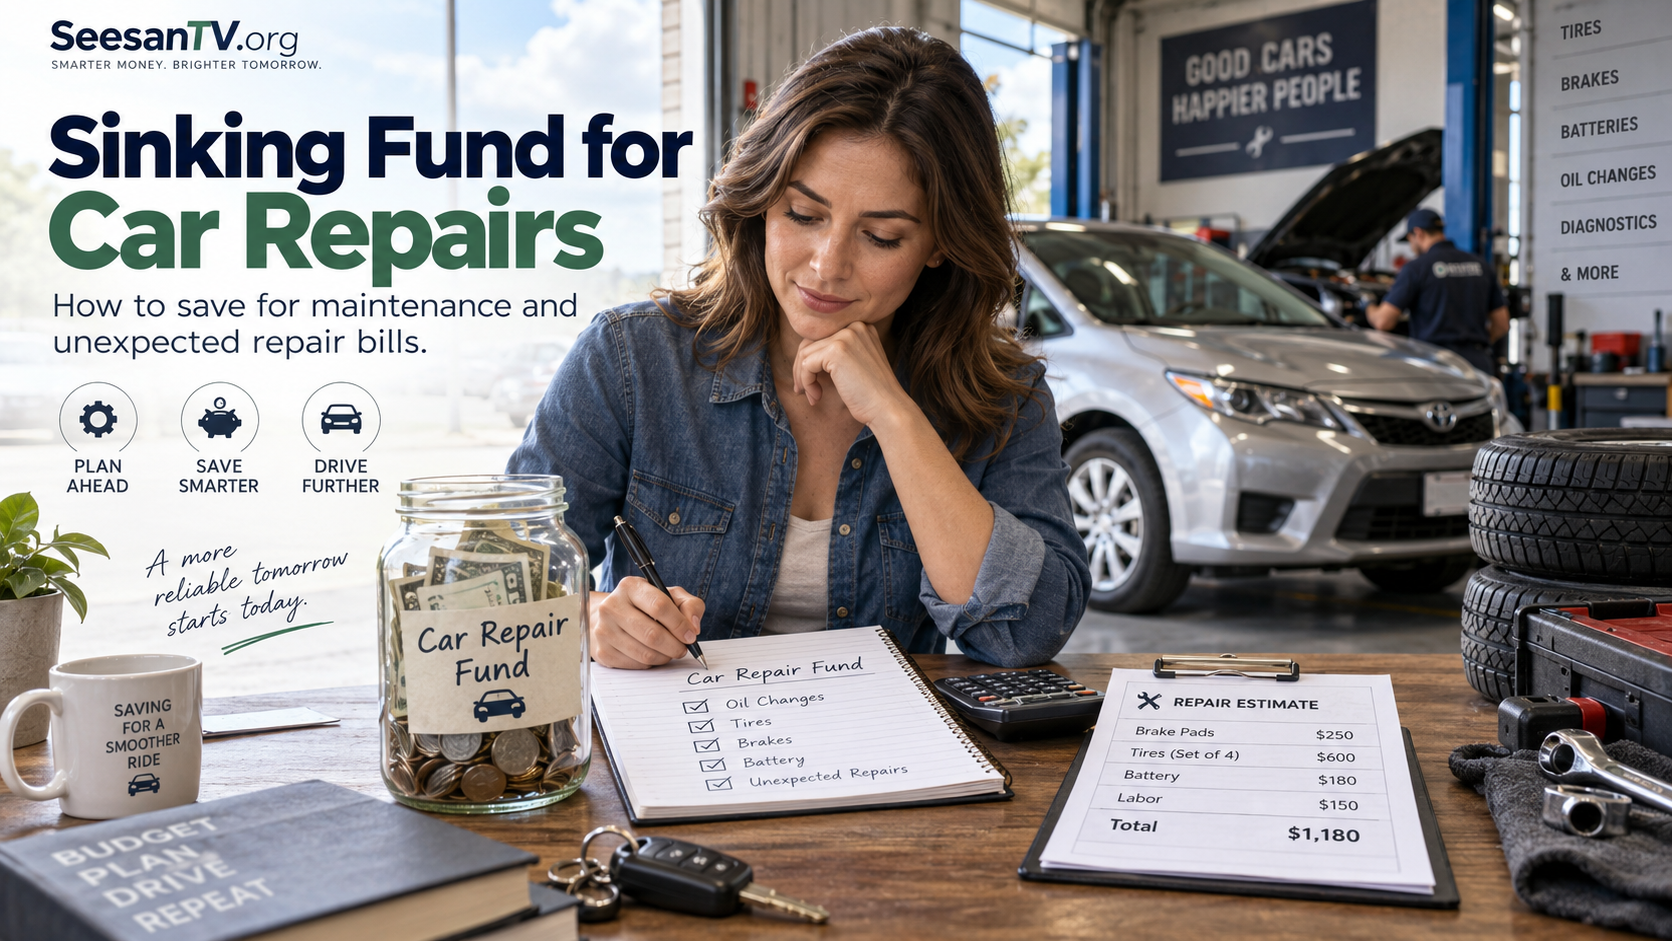
A sinking fund for car repairs is a separate pool of money built gradually to pay for maintenance, worn parts, and future repair bills without relying on a credit card or loan. For many drivers, starting with roughly $100 per month is reasonable, but the right amount depends on the vehicle’s age, mileage, reliability, warranty coverage, and repair history.
The idea behind Sinking Fund for Car Repairs on SeesanTV.org is simple: turn an unpredictable-looking car expense into a predictable part of your monthly budget. Cars eventually need tires, brakes, batteries, fluids, suspension work, and other repairs. You may not know the exact date those expenses will arrive, but you know they will not stay at zero forever.
That preparation matters more than it may seem. The Federal Reserve’s latest household survey found that 30% of U.S. adults experienced a major unexpected vehicle repair or replacement expense during 2025, making vehicle costs the most commonly reported major unexpected expense in the survey.
What Is a Sinking Fund for Car Repairs?
A car repair sinking fund is money reserved specifically for vehicle expenses that do not occur every month.
Instead of waiting for a $700 repair bill and then trying to find $700 immediately, you might save $75, $100, or $150 each month. When the repair eventually happens, at least part, and ideally all, of the money is already available.
A car sinking fund might cover:
- Brake pads and rotors
- Tires
- Battery replacement
- Alternator or starter repairs
- Suspension components
- Belts and hoses
- Cooling-system repairs
- Sensors and electrical problems
- Scheduled major services
- Smaller unexpected mechanical repairs
It can also cover insurance deductibles or towing if you intentionally include those expenses in your target.
The important point is that the money has one defined purpose. It is not simply extra cash sitting in your checking account.
Why Car Repairs Deserve Their Own Savings Fund
Car expenses are unusual because they fall somewhere between predictable and unpredictable.
You normally know tires will wear out. You know brake components eventually need replacement. An older battery will not last forever. What you usually do not know is whether the expense will arrive in March, July, or next year.
That makes a sinking fund particularly useful.
Recent Federal Reserve data shows why relying entirely on last-minute cash can be difficult. In 2025, only 63% of adults said they would cover a hypothetical $400 emergency using cash, savings, or a credit card paid off with the next statement. Twelve percent said they could not cover the $400 expense by any method.
A dedicated vehicle fund reduces the chance that a normal ownership expense becomes a financial emergency.
Sinking Fund vs. Emergency Fund
A sinking fund and an emergency fund are related, but they should not necessarily be treated as the same thing.
A sinking fund is built for a known category of future spending. A general emergency fund protects you from larger and less predictable financial shocks such as job loss, medical expenses, urgent home repairs, or a major vehicle problem that exceeds your normal repair reserve.
The Consumer Financial Protection Bureau specifically identifies car repairs as one of the expenses emergency savings may need to cover. It also emphasizes that even a small dedicated reserve can help people avoid turning a financial shock into additional debt.
A strong setup could therefore look like this:
Car maintenance budget: routine oil changes and regularly scheduled service.
Car repair sinking fund: tires, brakes, batteries and irregular mechanical work.
Emergency fund: major unexpected expenses that exceed the car fund.
You do not need three separate bank accounts to follow this approach. The separation can simply exist inside your budgeting system.
How Much Should You Put Into a Car Repair Sinking Fund?
There is no universal amount that works for every car.
However, AAA provides a useful starting point. Its car-repair budgeting guidance, updated in April 2026, estimates that maintenance, repairs, and tires average about 11.04 cents per mile for the vehicle assumptions used in its driving-cost analysis. Using average daily driving of 31.1 miles, AAA converts that to approximately $103 per month.
That makes about $100 a month a reasonable benchmark for many drivers, rather than a rule everyone must follow.
Your personal number may need to be considerably higher or lower.
A Simple Monthly Savings Formula
Use:
Target car fund minus current car savings ÷ months until target = monthly contribution
Suppose you want $1,500 available within one year and currently have $300 saved.
$1,500 − $300 = $1,200
$1,200 ÷ 12 = $100 per month
If your goal is starting from zero:
| Target Fund | Time | Monthly Saving |
|---|---|---|
| $600 | 12 months | $50 |
| $1,200 | 12 months | $100 |
| $1,800 | 12 months | $150 |
| $2,400 | 12 months | $200 |
| $3,000 | 12 months | $250 |
These are budgeting examples, not recommended minimum balances. Your vehicle should determine the target.
How to Set the Right Target for Your Particular Car
The best car repair sinking fund begins with your actual vehicle rather than a generic online number.
Check the Car’s Age
A relatively new vehicle with comprehensive warranty coverage normally creates a different financial risk than a 12-year-old vehicle with more than 150,000 miles.
AAA similarly advises owners of older vehicles to allow more room in their repair budgets because age and mileage can increase exposure to wear-related repairs.
Age alone does not predict whether a car will break, but it helps identify what may soon require attention.
Review the Mileage
Check your current odometer against the manufacturer’s maintenance schedule.
A vehicle approaching a period when tires, brakes, fluids, belts, plugs, filters, or other components are likely to require attention should have a larger short-term reserve than one that just completed major maintenance.
Do not rely solely on generic mileage intervals found online. Your owner’s manual or automaker’s maintenance schedule should be the primary reference for your model.
Look at Your Repair History
Review the previous 12 to 24 months.
Suppose you spent:
- $420 on brakes
- $180 on a battery
- $300 on routine maintenance
- $650 on an unexpected repair
Your total was $1,550.
Dividing $1,550 by 12 gives approximately $129 per month.
Past spending cannot predict every future failure, but it gives you a much more personalized starting point than an arbitrary budget.
Consider How Much You Drive
Someone driving 5,000 miles per year has a different wear profile from someone commuting 20,000 miles annually.
Higher mileage generally accelerates tire wear and moves the vehicle through maintenance intervals more quickly. Driving conditions also matter. Frequent short trips, heavy city traffic, poor roads, towing, extreme heat, and winter conditions can affect different components.
Check Your Warranty
Before setting aside money for every possible mechanical failure, understand what your warranty actually covers.
Check the manufacturer’s new-car warranty, powertrain coverage, certified-pre-owned coverage, or any legitimate extended service contract you purchased.
Wear items such as brakes and tires are commonly treated differently from mechanical defects, so do not assume everything is protected.
What Should Be Included in the Fund?
One useful method is to divide future vehicle expenses into three groups.
Predictable Maintenance
These expenses may include oil and filter changes, tire rotations, inspections, fluids, filters, spark plugs, and other manufacturer-specified maintenance.
Because you roughly know when these costs are coming, they are ideal sinking-fund expenses.
Wear Items
Tires, brake pads, rotors, batteries, wiper blades, and some suspension components gradually wear down.
Their exact replacement date may not be known, but they are not truly surprising expenses.
AAA’s April 2026 guidance provides examples of the wide variation in vehicle costs. It lists tires at $200 or more per tire in some cases, brake-pad replacement around $300 per axle, and battery replacement roughly between $75 and $200 before any applicable labor. Costs vary substantially by vehicle, parts, location, and repair shop.
Unexpected Repairs
A failed alternator, coolant leak, starter problem, electrical failure, or transmission issue can arrive with much less warning.
AAA notes that some larger repairs can run into the thousands of dollars. Its current budgeting guide gives an illustrative transmission replacement range of roughly $2,500 to $6,000, showing why even a well-funded sinking account may occasionally need support from a broader emergency fund.
A Practical Sinking Fund System
A complicated budgeting system is unnecessary.
Start by deciding on a realistic target. Then create a monthly contribution that fits the rest of your financial obligations.
For example, imagine your goal is $2,000.
You deposit $125 per month. After 12 months, you have contributed $1,500. If a $400 brake repair occurs, you pay from the fund and continue making your normal $125 monthly deposits afterward.
The account does not need to return instantly to $2,000. You simply begin replenishing it.
This is what makes sinking funds sustainable. The fund is supposed to be used.
Automate the Savings
Automatic transfers make the process much easier.
The CFPB recommends automatic deposits as one method of building savings, such as arranging recurring transfers from checking to savings shortly after a paycheck arrives.
For example, if your monthly target is $120 and you are paid twice monthly, you could automatically move $60 from each paycheck.
The transfer then becomes part of your normal financial routine instead of a decision you need to make repeatedly.
Where Should You Keep a Car Repair Sinking Fund?
Car-repair money should usually remain accessible because you cannot predict exactly when the repair will happen.
A separate savings account is one of the simplest options. It prevents repair money from being mixed with normal spending while keeping it available when needed.
For U.S. consumers, savings accounts and money market deposit accounts at FDIC-insured banks are covered by federal deposit insurance, subject to applicable ownership rules and limits. The standard amount is $250,000 per depositor, per FDIC-insured bank, per ownership category.
For a short-term vehicle reserve, accessibility and capital preservation generally matter more than trying to earn investment returns.
Money that could be needed for next month’s transmission repair is different from money being invested for retirement decades from now.
Should You Save $50, $100, or $200 a Month?
Start with the amount your vehicle and budget support.
$50 per month builds $600 in a year.
That may help with smaller repairs and maintenance, although it will not cover every significant mechanical problem.
$100 per month builds $1,200 annually.
This is close to AAA’s roughly $100 monthly maintenance-and-repair budgeting benchmark and is a practical starting point for many drivers.
$200 per month builds $2,400 annually.
That may be appropriate when an older or high-mileage car has significant upcoming work, when you drive heavily, or when previous repair history indicates higher costs.
The correct contribution is the one supported by evidence from your own car.
Build the Fund Around Upcoming Repairs
A good sinking fund does not need to be based solely on averages.
Suppose an inspection shows that you are likely to need approximately:
Tires: $900
Brakes: $500
Scheduled maintenance: $250
Repair cushion: $550
Your total target becomes $2,200.
If the work is likely within 10 months:
$2,200 ÷ 10 = $220 per month
That plan is far more useful than blindly saving $100 simply because an average suggests it.
Do Not Ignore Preventive Maintenance to Save Money
Skipping maintenance can make a monthly budget look better temporarily, but it is not a sound sinking-fund strategy.
Routine inspections and timely maintenance can reveal worn components before a small problem becomes a more expensive failure. AAA recommends regular inspections and responding quickly to warning lights, sounds, or other symptoms as part of managing repair costs.
Your sinking fund should make maintenance easier to afford, not become a reason to postpone it.
Check for Recalls Before Paying for Certain Repairs
Before paying for a problem that might involve a safety defect, check whether your vehicle has an open recall.
The National Highway Traffic Safety Administration allows U.S. owners to search open recalls using a VIN or, for supported searches, a license plate. NHTSA states that safety-recall remedies are provided free through the vehicle manufacturer or authorized dealership.
This matters because spending several hundred dollars from your repair fund on a covered recall could be unnecessary.
Check the recall status first when the suspected component may be affected.
Get an Estimate Before Authorizing Repairs
Having savings available does not mean accepting the first repair price you receive.
The Federal Trade Commission recommends asking for a written estimate. It says the estimate should identify the condition being repaired, necessary parts, and anticipated labor charges, while specifying when additional authorization is required for work that exceeds an agreed amount. State requirements can vary.
For an expensive non-emergency repair, a second opinion may also be worthwhile.
Ask questions such as:
- Which repair is safety-critical?
- Which work can reasonably wait?
- Are the proposed parts new, remanufactured, rebuilt, or used?
- What warranty applies to parts and labor?
- Is there a diagnostic fee?
- Does the estimate include taxes and shop fees?
This helps protect the sinking fund from unnecessary spending.
What If You Cannot Afford $100 Per Month?
Start smaller rather than abandoning the idea.
Saving $25 per month creates $300 after a year. Saving $40 creates $480. Neither amount can handle every mechanical failure, but either can reduce how much you need to borrow when a repair happens.
The CFPB emphasizes that even small savings can provide meaningful financial protection and that an emergency savings target should reflect an individual’s circumstances.
You can increase the contribution later after paying off debt, receiving a raise, reducing another expense, or finishing a different savings goal.
Windfalls can help as well. Part of a tax refund, bonus, gift, or other one-time income can quickly establish the initial balance.
What Happens When the Fund Reaches Its Goal?
You do not necessarily need to keep increasing it forever.
Once the fund reaches the amount you consider adequate for your current vehicle, you can reduce or temporarily pause contributions and redirect the money toward another priority.
Continue reviewing the target, however.
A car that was five years old when you established the fund will eventually be eight, ten, or twelve years old. The repair reserve that was sufficient earlier may no longer match the vehicle’s risk profile.
Reassess the target at least when your mileage, warranty status, driving pattern, or repair history changes significantly.
When Should You Use the Car Repair Fund?
Use it for expenses that match the purpose you established.
A new battery after the old one fails fits. Brake replacement fits. A required suspension repair fits.
A new set of cosmetic wheels probably does not, unless upgrades were explicitly part of your savings goal.
Clear rules prevent the account from slowly becoming another general spending account.
When a Repair Is Larger Than the Sinking Fund
No sinking fund can guarantee that every repair will be affordable.
If you have $1,500 saved and receive a $4,000 repair estimate, first verify the diagnosis, warranty status, recall status, and repair price. Then consider the vehicle’s market value, overall condition, other expected repairs, and how long you realistically plan to keep it.
Sometimes paying for a major repair makes financial sense. In other situations, repeatedly investing large amounts into a deteriorating vehicle may not.
That decision should be based on the complete financial picture rather than the repair bill alone.
What “Sinking Fund for Car Repairs on SeesanTV.org” Means
The target phrase Sinking Fund for Car Repairs on SeesanTV.org is best understood as a search for guidance on creating a dedicated car-repair savings reserve.
SeesanTV.org itself currently presents a mixture of entertainment and general editorial content. Its public pages do not identify the site as a bank, registered investment adviser, lender, or government financial agency. Financial figures in this guide therefore rely primarily on current information from organizations such as the Federal Reserve, CFPB, AAA, FTC, FDIC, and NHTSA rather than treating SeesanTV.org as an authoritative financial source.
The budgeting examples above are educational rather than personalized financial advice. Your actual savings target should reflect your vehicle, income, other savings, debt obligations, insurance, and overall financial situation.
FAQ
How much should I save each month for car repairs?
Around $100 per month can be a useful starting benchmark, based on AAA’s current guidance for typical maintenance, repair, and tire costs. Your amount should be adjusted for your car’s age, mileage, warranty, annual driving, previous repairs, and known upcoming work.
Is $1,000 enough for a car repair fund?
It can provide a useful cushion for many smaller and mid-sized expenses, but it cannot guarantee coverage of a major mechanical failure. Some repairs can cost several thousand dollars, so drivers with older or higher-mileage vehicles may choose a larger target.
Is a car sinking fund the same as an emergency fund?
No. A car sinking fund is earmarked specifically for vehicle expenses that are expected eventually, even when their exact timing is unknown. An emergency fund is broader and can protect against job loss, medical costs, major home expenses, or a car repair that exceeds the vehicle fund.
Should car maintenance come from the sinking fund?
It can. Some people keep routine maintenance and repairs in the same vehicle account, while others maintain separate budget categories. Either approach works as long as scheduled maintenance has already been included in the amount being saved.
Where should I keep my car repair money?
It should generally be somewhere safe and readily accessible, such as a separate savings account. If using a U.S. bank, verify that it is FDIC insured and understand the applicable deposit-insurance rules.
What should I do before paying for a major car repair?
Check warranty and recall coverage, request a written estimate, understand the parts and labor being proposed, and consider a second opinion for expensive work when practical. NHTSA says qualifying safety-recall repairs are free, while the FTC recommends obtaining detailed written repair estimates.
For more about SeesanTV.org, click here.

2 Comments
Pingback: Passkey vs Password Manager: SeesanTV.org Guide for Safer Logins in 2026
Pingback: 8.3 independent practice page 221 answer key: Percent Solutions